Composable banking is an approach that emphasises flexibility and agility by allowing banks to assemble and reassemble modular banking capabilities quickly and easily. Each capability is an independent component with its own logic and data, joined to the others through open APIs. It replaces the monolithic core, where every product, process and ledger function ships as a single system, from a single vendor, on a single release cycle.
Composable banking vs modular banking
Almost every core banking vendor now describes its product as modular. The words are close enough that the distinction gets lost in a shortlist, and this is where the meaning of composable banking matters commercially rather than academically.
| Dimension | Modular banking | Composable banking |
|---|---|---|
| How modules are defined | By the vendor, as divisions of one product | By business capability, each independently deployable |
| Who owns the integration | The vendor, internally and invisibly to the bank | The bank, through documented open APIs |
| Swapping a component | Depends on the vendor roadmap, usually a re-implementation | Replace one component, the contract at the API stays the same |
| Vendor lock-in | At the platform level | At the component level |
| Time to a new product | A release cycle | Assembly and configuration |
The test is simple to apply and uncomfortable to answer. Take one component, a pricing engine or a limits engine, and ask what happens if the bank wants to replace it with a competitor’s next year. In a modular system the honest answer is that it cannot be done without opening the whole platform. In a composable one the component is bounded by an API contract, and replacing it is a scoped piece of work with a defined blast radius.
Modularity is a description of how a product is organised. Composability is a description of what the bank can do to it afterwards.
How composable banking actually works
A composable architecture has a coordinating core and a set of independent components around it, communicating over open APIs and events rather than shared database tables.
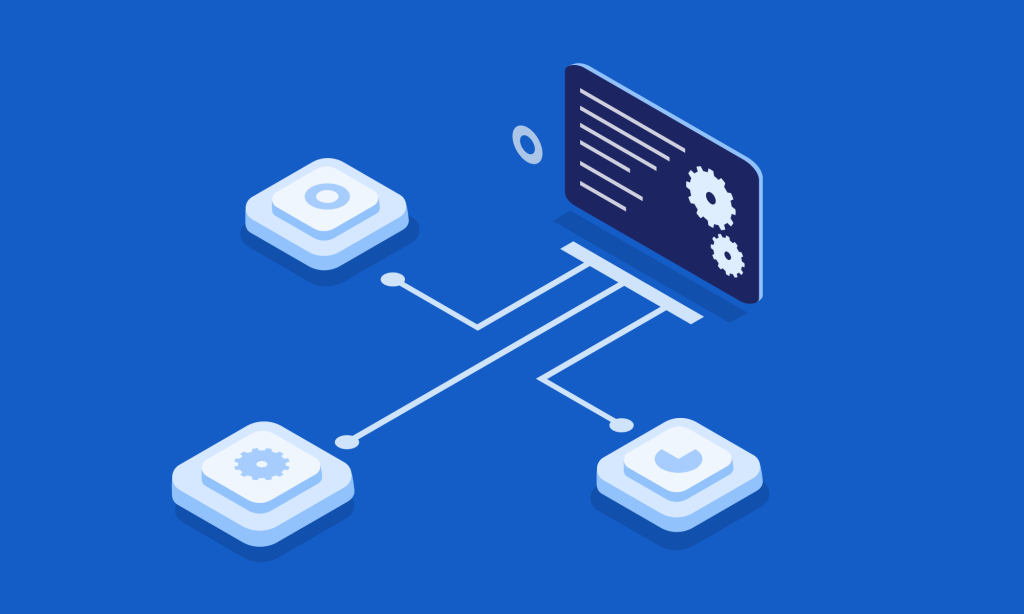
The core keeps a deliberately small set of responsibilities. It holds the ledger and the accounting record. Enforces double entry. Which is the single source of truth for balances and positions, and it publishes an event whenever that truth changes. Everything that reads or acts on those events sits outside it.
A component, in this context, is a capability with its own logic and its own lifecycle. A product engine that defines what a financing product is and how it behaves. A limits engine. A pricing engine. A party and customer store. A collections capability. Each can be released on its own schedule, and each is reachable through the same API surface the bank’s own developers use.
What leaves the core is everything the core was never good at holding: channels, onboarding, credit scoring, document handling, distribution partners, analytics. These change far faster than a ledger should, and putting them inside a core banking release cycle is what made legacy modernisation programmes take years.
The result is an operating model rather than a product. This is why composable banking is sometimes described as a composable banking operating system: the bank assembles capabilities, and the platform coordinates them, keeps the record and enforces the rules.
What composable banking costs you
Every article on this subject lists the benefits. Fewer are honest about what a bank takes on, and a transformation lead scoping a replacement already knows there is a bill.
More integration surface. Independent components mean more contracts between systems. Each one is a place where a version can drift, a timeout can happen and an error has to be handled deliberately rather than inside a vendor’s black box.
More vendors to manage. Component-level choice means component-level procurement, contracts and renewals. The lock-in moves from one large relationship to several smaller ones, which is better commercially and heavier operationally.
Harder failure analysis. And when a payment fails in a monolith, one vendor owns the answer. Across a composed estate, tracing a failure means correlating events across boundaries, which requires proper observability from day one rather than as a later phase.
Reconciliation discipline. Distributed components need one unambiguous system of record. If two components can both claim to hold the balance, the architecture has recreated the problem it was meant to solve.
Architecture capability in-house. Composability moves real decisions to the bank. That is the point of it, and it only pays off if there is someone on the bank’s side to make those decisions.
None of this argues for staying monolithic. But it argues for choosing composability deliberately, with the operating model planned alongside the architecture, rather than discovering the bill in the second year of the programme.
What is a composable banking platform?
A composable banking platform is the coordinating layer plus the set of independently deployable components: a ledger and accounting core that holds the record, product, pricing, limits and party capabilities that can be assembled into propositions, and an open API surface through which the bank and third parties reach all of it. A composable core banking platform is the same idea narrowed to the functions a licensed institution has to keep inside its own regulatory perimeter.
In which practical marker is whether the bank can launch a product by configuring one rather than by commissioning one. Fimple’s composable platform is built on that principle, as an AI-native, API-first, composable financial platform serving banks, participation banks, NBFIs and fintechs.
Composable banking in practice
Two deployments show what assembly looks like, and they sit at opposite ends of the question.
Dünya Katılım, Türkiye: building from nothing. Fimple launched the core banking platform at this participation bank in one and a half months, a participation bank platform stood up in six weeks (Fimple announcement, January 2024). The architectural reason that was possible is that participation banking contract types are product definitions in the platform rather than a compliance layer wrapped around conventional instalment logic. The bank configured a product set instead of commissioning one, which is what assembly means in practice.
Mawarid Finance, United Arab Emirates: adding to what exists. Mawarid Finance and Fimple announced a strategic agreement at the Mawarid Fintech Summit in June 2026, with Fimple operating as a Side Core Banking layer integrated with Mawarid’s existing infrastructure. The institution gains banking-as-a-service and new product capability without replacing the core it already runs.
That second case is the one worth sitting with, because it is the argument against the false choice most modernisation business cases are built on. Composability does not require a migration. A new capability can arrive as a component alongside the existing core, which means the decision can be taken one capability at a time rather than as a single multi-year commitment.
What to ask a vendor
Put these to any platform on the shortlist, including this one. The answers separate composable from modular faster than a feature matrix will.
Can I replace one component with a competitor’s product without reopening the platform contract? If not, the modularity is internal to the vendor and not available to the bank.
Is the API you expose to me the same API your own product teams build on? A separate integration API means a second-class path, and it will lag.
Can I define a new product without a vendor release? Ask to see it done on a call, on a product the vendor has not prepared.
Where does the balance live, unambiguously? There should be one answer, and it should be short.
What happens to my data if I leave? Export format, event history, and whether the ledger is reconstructable outside the platform.
Which of your claimed deployments can I speak to, by name? Reference architecture is a diagram. A named institution in a comparable regulatory environment is evidence.
Where to go next
Composable banking is an operating model before it is a technology choice, and the decision that follows the definition is an architectural one: what stays inside the core, what moves out, and in what order the migration runs.
For the commercial case, including where the savings actually come from, see the economics of composable banking. To see how the components fit together in one platform, start with the composable platform overview.